Weekly sustainability insights can now be found by following this link: Sustainability Corner
NOTE: We will not be sending the Energy Market Update the week of November 23. We will return the week of November 30.
Weekly Energy Industry Summary
Commodity Fundamentals
Week of November 16, 2026
- Prompt-month (December) natural gas settled at $3.12/MMbtu, down $.11, on Monday, November 16.
- Prompt-month crude (WTI) settled at $85.22/bbl., down $2.84, on Monday, November 16.
Natural Gas Fundamentals - Neutral/Bearish
- Bearish weather forecasts continue to keep a lid on natural gas pricing action.
- October was the 4th warmest on record, dampening residential/commercial demand followed by a November that so far has ranked in the top ten warmest since 1950.
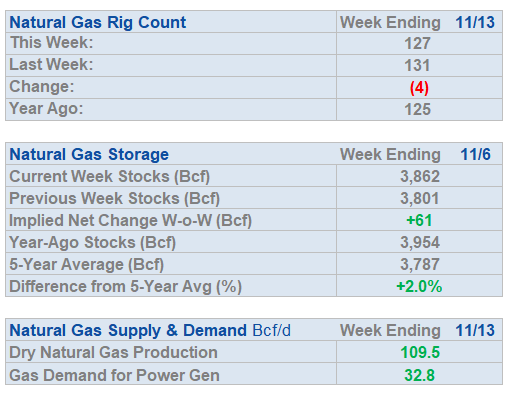
- Residential/commercial demand for natural gas, month-to-date, averaged 22.1 Bcf per day versus 24.2 one year ago.
- Power generation demand, month-to-date, averaged 33.5 Bcf per day versus 30.2 one year ago.
- LNG feedgas volumes month-to-date, averaged 21 Bcf per day versus 19 one year ago.
- Production of natural gas month-to-date averaged 109.9 Bcf per day, versus 108.6 one year ago; Year-to-date, natural gas production averaged 110.2 Bcf per day, versus 106.2 for the same period last year.
- Storage inventories are currently 3.86 Tcf, and a further injection is forecast for this week.
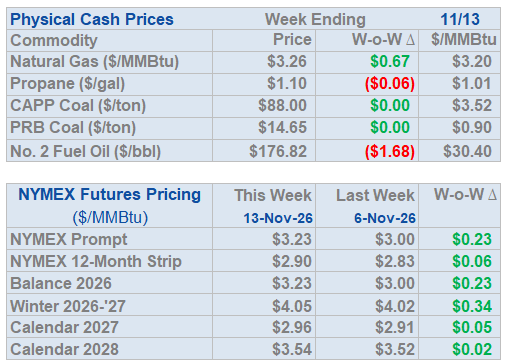
- 2027-31 NYMEX strip prices are: $2.94, $3.53, $3.62, $3.64 and $3.62 respectively. The 2027 strip continues to trade near its four-year low.
Crude Oil - Bullish
- Point of Clarification: The "Bullish" moniker above will remain in place until further notice as the situation in the Persian Gulf remains highly unstable.
- Prompt-month crude (WTI) settled at $85.72/bbl., down $2.84 yesterday.
- Over the past 30 days through November 10, crude oil flows from the Persian Gulf region averaged 19.2 million barrels per day: the pre-war level was 19.9 million barrels per day; 11.6 million barrels per day flowed through the Strait of Hormuz and 7.6 million barrels per day flowed through pipelines.
- In October, 4.2 Bcf per day of LNG flowed through the Strait; 38% of pre-war levels.
- In October, 1.9 million barrels per day of refined crude products flowed through the strait; pre-war the average was 4.8 million barrels per day.
- In October, 37 ships were attacked in the Persian Gulf region, the most attacks since the early phase of the war.
Economy - Neutral
- St. Louis Fed President Alberto Musalem said Tuesday that the Fed may need several interest-rate increases before spring 2027 arguing that monetary policy is not restrictive enough to bring inflation under control.
- October retail sales increased 0.2% compared with 0.8% in September.
- Auto sales declined 1.6%, furniture sales were down 2.3% while core sales, excluding several volatile categories rose a healthier 0.6%.
- Homebuilder confidence has fallen to its lowest level in more than 14 years.
- Housing starts, jobless claims and consumer sentiment data will be released this week.

Weather - Neutral
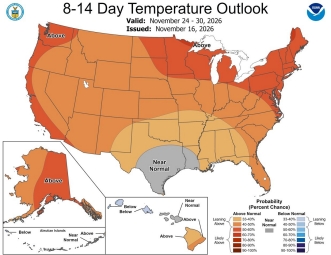
- A gradual warming trend in the East takes place this week with a return to more seasonal air next week.
- Storminess and below-normal temperatures will present in the West this week.
- There is not a lot of cold Canadian air to link to the jet stream in the lower-48.
- It will be modestly below normal in the Southeast this week.
Weekly Natural Gas Report
- Inventories of natural gas in underground storage for the week ending November 6 are 3,862 Bcf; an injection of 61 Bcf was reported for the week ending November 6. Stocks were 92 Bcf lower than this time last year and 75 Bcf above the five-year-average.
Weekly Power Report:
Mid-Atlantic Electric Summary
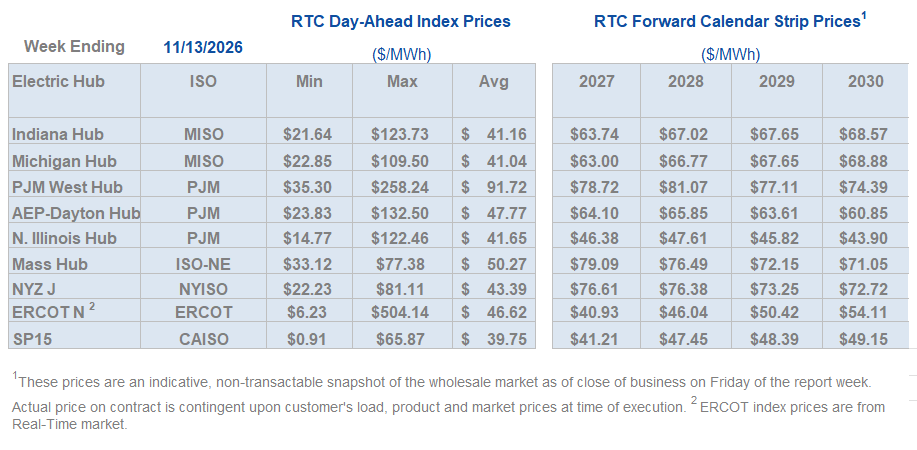
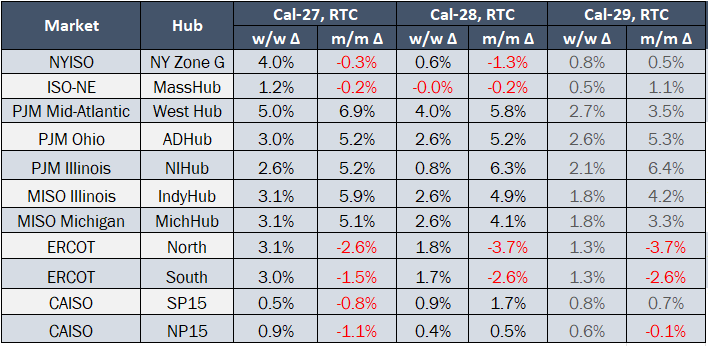
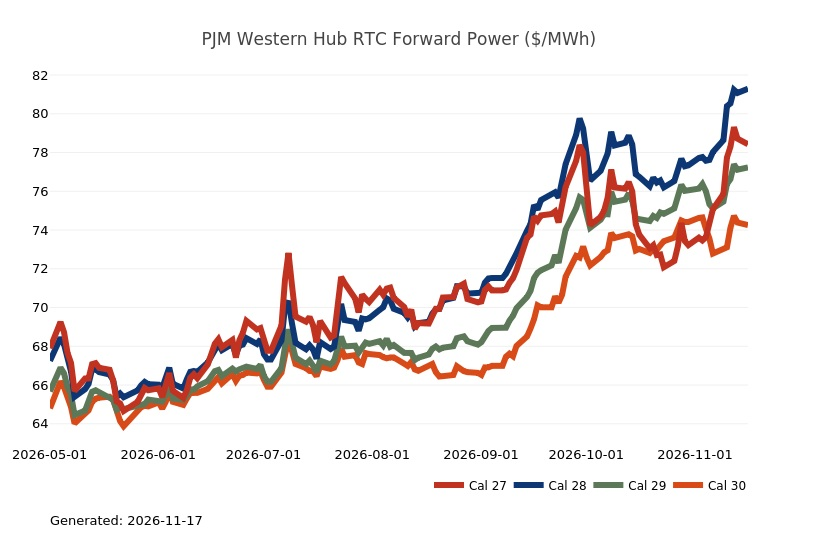
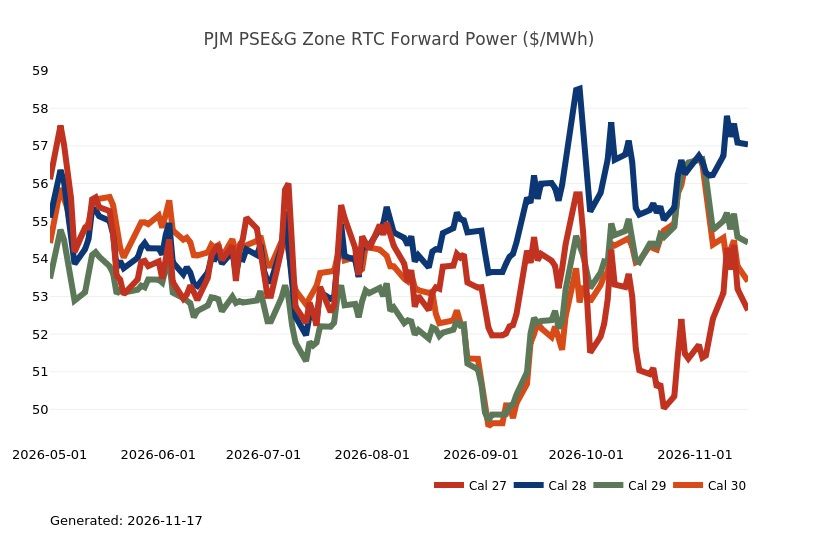
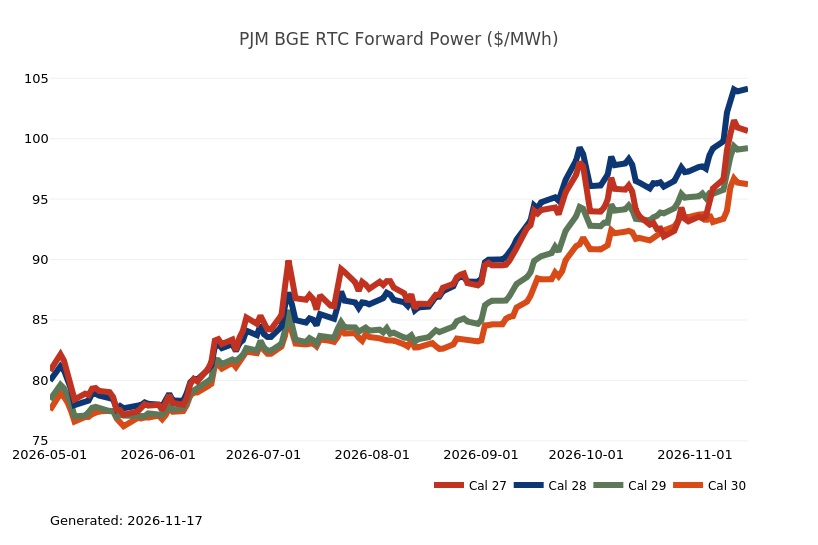
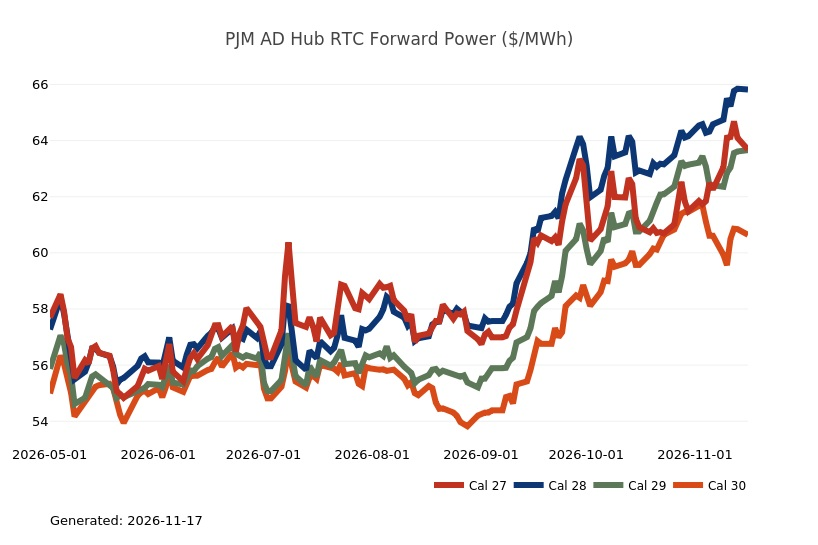
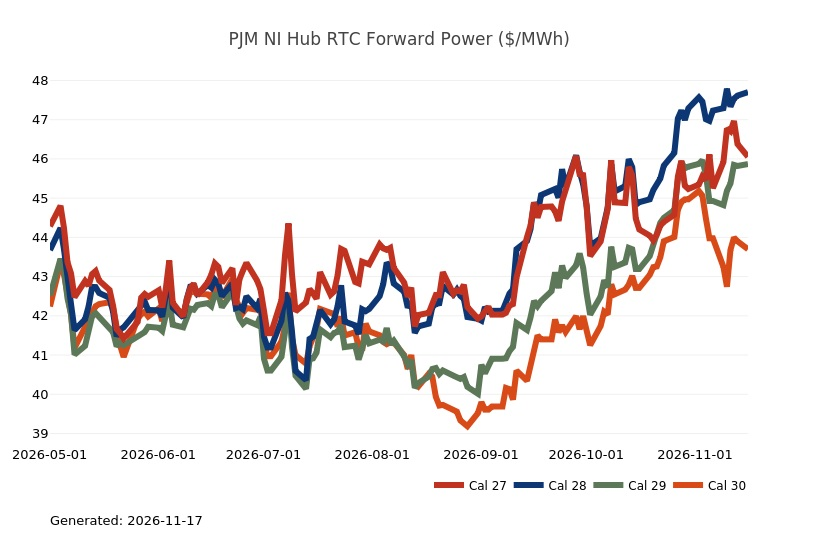
- The Mid-Atlantic Region’s forward power prices were higher on the week, along with natural gas prices, due to colder demand projections for this week. The December NYMEX natural gas contract settled lower on Monday, as a bearish storage injection last week, higher gas production and a mild back-half November demand forecast outweighed robust LNG demand. This weekend's chill in the East will fade this week, with a faster return to milder conditions with above-normal temperatures returning to the forecasts. This is due in part to a deeper cooling trough and increased storminess in the West. The models suggest that a more invigorated southern jet stream could bring storms up the East Coast toward the end of November, followed by a stronger eastern trough. Forward power prices in the Mid-Atlantic were 2% higher on the week, with 2%-3% increases on the 2027/29 terms and only 1% increases for the 2030-2031 terms. The current, month-to-date average settlement price in West Hub is $79.10/MWh or 16% higher than the final price average for October.
- OPSI and OH Present Feedback on PJM Holistic Market Reforms - At the 11/13 Powering Reliability Through Market Design Workshop, Organization of PJM States (OPSI) Director Ben Sloan presented OPSI’s Market Reform Principles, and Tim Benedict of the Public Utilities Commission of Ohio (PUCO) presented a summary of the Ohio Statement on PJM Market Reforms. Both OPSI and the PUCO advocated for maintaining central capacity procurement with a greater role for voluntary hedging, while also suggesting several key reforms. OPSI supports maintaining a central capacity market while emphasizing the need for flexibility during the current resource adequacy challenges, including both voluntary flexibilities, through non-firm transmission service and potentially expanded demand response, and involuntary curtailments for large loads that contribute to scarcity conditions. OPSI further advocated for an expanded role for voluntary hedging and spreading forward commitments over time to reduce volatility, while opposing a uniform regional hedging mandate. OPSI also supports a seasonal capacity construct, shifting the focus from penalties for non-performance to compensation for actual performance, ELCC reforms and accreditation stabilization, an expedited interconnection queue, and evaluation of transmission and generation solutions together. OPSI expressed general support for energy and ancillary service (E&AS) reforms to better reflect scarcity conditions but stressed the need for a “circuit breaker” that could be engaged to protect customers from extreme scarcity pricing, as well as the need to appropriately reflect E&AS revenues within RPM pricing.
Great Lakes Electric Summary
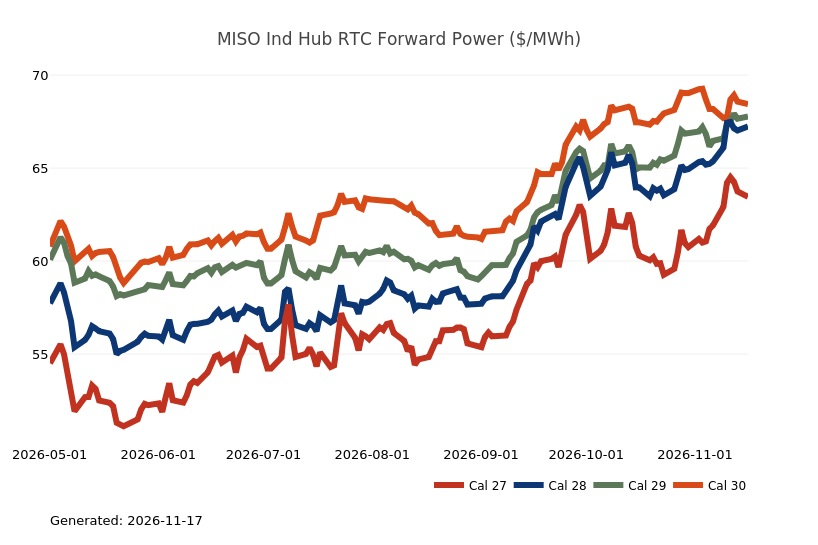
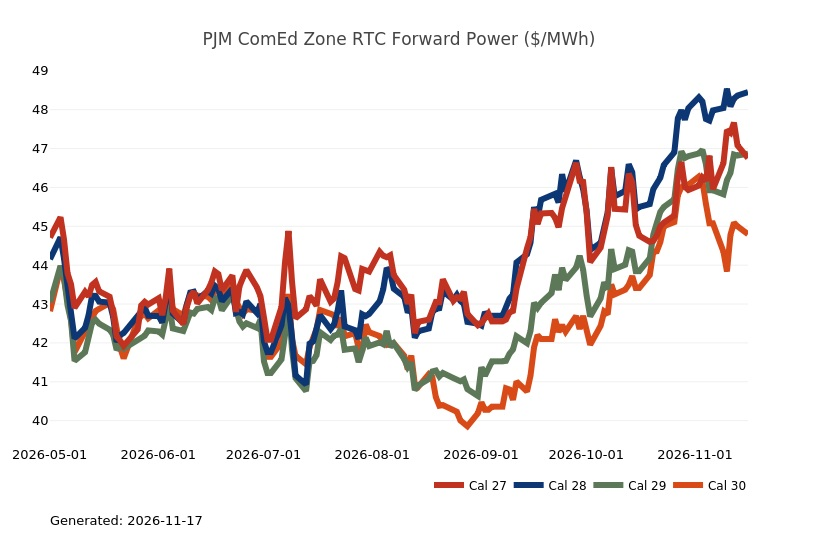
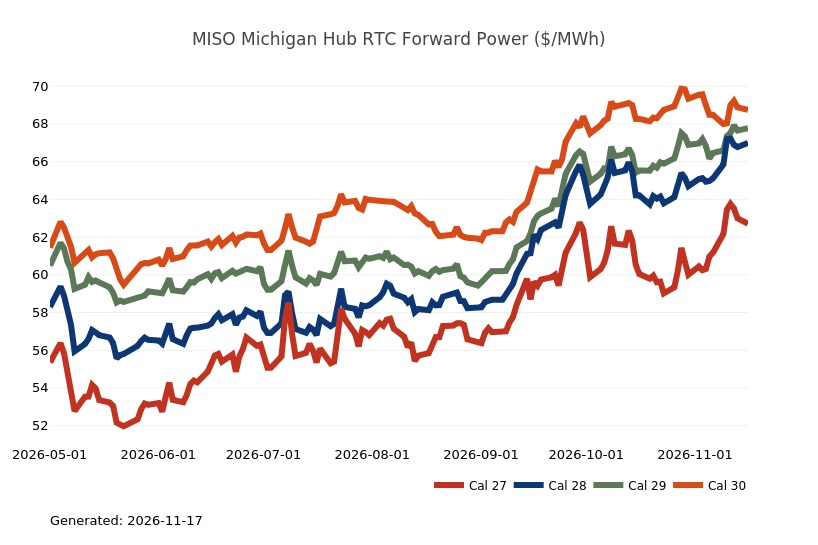
- The Great Lakes Region’s forward power prices were higher on the week, along with natural gas prices, due to colder demand projections for this week. The December NYMEX natural gas contract settled lower on Monday, as a bearish storage injection, higher gas production and a mild back-half November demand forecast outweighed robust LNG demand. This weekend's chill in the East will fade this week, with a faster return to milder conditions with above-normal temperatures returning to the forecasts. This is due in part to a deeper cooling trough and increased storminess in the West. The models suggest that a more invigorated southern jet stream could bring storms up the East Coast toward the end of November, followed by a stronger eastern trough. Forward power prices in the GLR were 1% higher on the week, with 2%-3% increases in the 2027/29 terms and were unchanged for the 2030-2031 terms. The current, month-to-date average settlement price in COMED is $36.46/MWh or -30% lower than the final price average for October, while in AdHub the average price is $48.51/MWh or -24% lower than last month’s average price. In Michigan the month-to-date price average thus far is $39.95/MWh or -27% lower than October’s final settlement price average, while in Ameren the price is averaging $34.55/MWh or -30% lower than the prior month’s final average price.
- OPSI and OH Present Feedback on PJM Holistic Market Reforms - At the 11/13 Powering Reliability Through Market Design Workshop, Organization of PJM States (OPSI) Director Ben Sloan presented OPSI’s Market Reform Principles, and Tim Benedict of the Public Utilities Commission of Ohio (PUCO) presented a summary of the Ohio Statement on PJM Market Reforms. Both OPSI and the PUCO advocated for maintaining central capacity procurement with a greater role for voluntary hedging, while also suggesting several key reforms. OPSI supports maintaining a central capacity market while emphasizing the need for flexibility during the current resource adequacy challenges, including both voluntary flexibilities, through non-firm transmission service and potentially expanded demand response, and involuntary curtailments for large loads that contribute to scarcity conditions. OPSI further advocated for an expanded role for voluntary hedging and spreading forward commitments over time to reduce volatility, while opposing a uniform regional hedging mandate. OPSI also supports a seasonal capacity construct, shifting the focus from penalties for non-performance to compensation for actual performance, ELCC reforms and accreditation stabilization, an expedited interconnection queue, and evaluation of transmission and generation solutions together. OPSI expressed general support for energy and ancillary service (E&AS) reforms to better reflect scarcity conditions but stressed the need for a “circuit breaker” that could be engaged to protect customers from extreme scarcity pricing, as well as the need to appropriately reflect E&AS revenues within RPM pricing.
Northeast Energy Summary
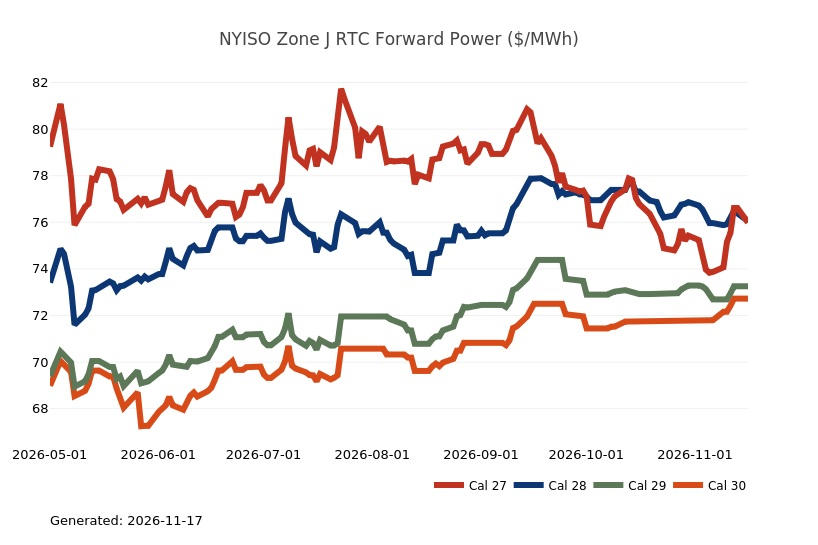
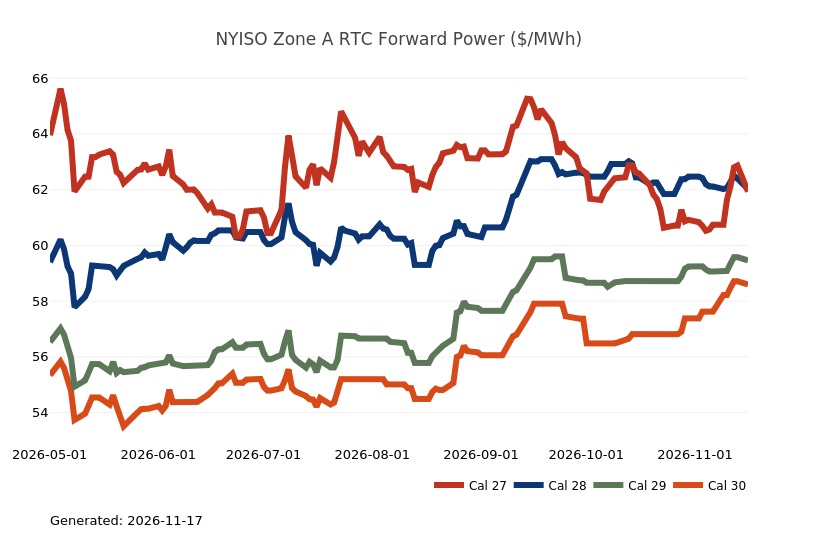
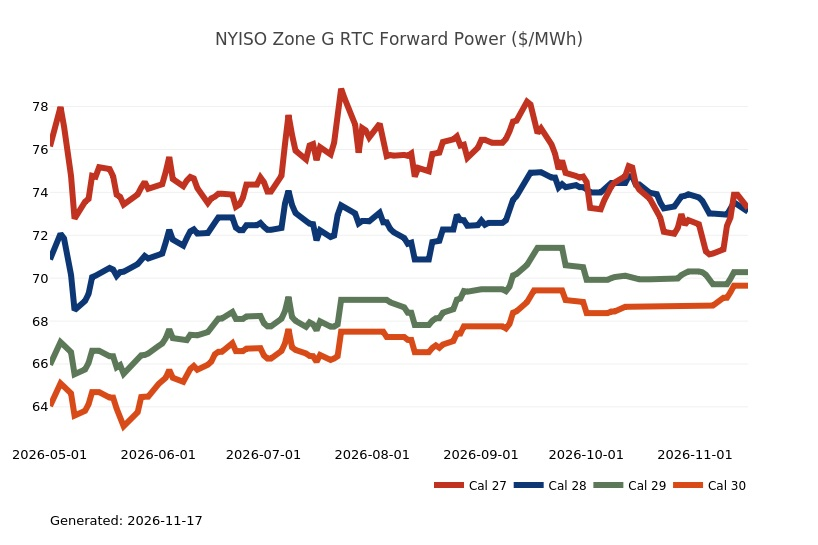
- Several months back, the Federal Energy Regulatory Commission (FERC) issued show cause orders to each of the six RTO/ISOs (and their transmission owners) inquiring as to whether existing RTO/ISO and transmission owner tariffs are just and reasonable absent provisions specifically addressing large load interconnections and service and, if not, requiring the RTO/ISO and transmission owners to file changes to address large loads. On November 13, ISO New England filed its comprehensive response at FERC. The proposal includes a requirement that all new large loads build or contract with new capacity resources or be subject to curtailment whenever the energy market price reaches $250/MWh. NYISO -- and potentially SPP and MISO – may submit similar price-based curtailment protocols at FERC next week in their own show cause order responses.
- On November 10, The Kraft Group proposed a data center development in Sutton, MA. The completed project would have approximately 900 MW in peak demand. This is the first major proposal for a data center in Massachusetts since Governor Maura Healey issued Executive Order No. 658 (EO 658) in September which imposes strict clean-energy additionality and ratepayer-protection mandates on large load developments in the state. EO 658 will require this project to secure a Community Benefits Agreement (CBA) before any state agency may issue a permit. At the Sutton Select Board Meeting, where this project was first disclosed, residents expressed concern over water use, electricity rate impacts, and backup generator noise. Town officials described the benefits of additional tax revenue from the $16.75 billion project, which would generate $27.8 million in annual tax revenue when the project is complete and emphasized that the additional tax revenue would lower tax bills for residents and alleviate the budget gap in the town’s financial plans starting in 2031. The Kraft Group has entered into preliminary discussions with ISO New England. However, the project is still in early stages and would likely need a full Planning Board hearing, a two-thirds Town Meeting approval, and a finalized CBA before it can get state permits.
- NYISO Management Committee Approves Large Load Proposal Responding to FERC Show Cause Order - On 10/28, stakeholders approved NYISO’s proposal for large and co-located loads in response to FERC’s Show Cause Order, with a roll-call vote of 100% in favor and numerous abstentions. Board action is expected in November, followed by a planned 11/16 Section 205 filing with FERC. The proposal seeks to accelerate load and generator interconnection, strengthen transmission security and resource adequacy studies, and prevent cost shifts by ensuring large loads pay for the network upgrades they cause, particularly in co-location arrangements. NYISO described its consumer protections as shielding customers from unnecessary market costs and improving interconnection cost transparency.
- To address potential resource adequacy impacts, the Large Load Integration Procedures (LLIP) proposal approved Wednesday requires large loads of 50 MW or more to bring corresponding new capacity or face curtailment. Non-Firm Withdrawal Service also caps energy market bids at $200/MWh, effectively curtailing those loads when the transmission system is constrained. The proposal also imposes stricter metering, telemetry, and remote-control requirements on Large and Co-Located Loads, including remote disconnect capability, a ramp-rate limit of 100 MW per five minutes, and a system-wide Large Load Ramp Rate still to be determined. The proposal does not specifically address Load-Contingent New Capacity at Existing Plants.
- The proposal also includes a mechanism that the state could use to exempt a specified large load from the new requirements, developed in response to Department of Public Service staff and stakeholder feedback. Exemptions cannot cause a resource adequacy violation in the first five years of the planning horizon, and exempt projects must still complete NYISO’s study process and transmission security tests. Eligibility will be determined through the Public Service Commission’s ongoing Large Load proceeding (Case 26-E-0045). In the interim, all projects remain subject to the standard NYISO process.
- NYISO Reliability Needs Assessment Advances, Identifies Shortfalls Starting in 2032 - On 10/28, the NYISO Management Committee approved the 2026 Reliability Needs Assessment (RNA), identifying three reliability needs within the 10-year planning horizon and translating years of warnings into actionable findings. New York City’s summer shortfall begins at 400 MW for 7 hours in 2032 and reaches 1,850 MW for 15 hours by 2036. The Hudson Valley’s summer shortfall grows from 130 MW for 2 hours in 2032 to 1,950 MW for 7 hours by 2036. A separate statewide resource deficiency begins at 225 MW in 2033 and exceeds 1,850 MW by 2036.
- The RNA assumes 6,200 MW of new solar, wind, and storage enters service through 2036; New York Power Authority’s roughly 517 MW of small New York City peaker plants retire in 2031 under the 2023 Build Public Renewables law; and 5,400 MW of gas units without firm fuel contracts are unavailable in winter. It includes 2,700 MW of new large loads but excludes more than 12,000 MW of additional large loads in NYISO’s interconnection queue, primarily AI data centers. The assessment also reflects reduced emergency import support as neighboring regions face tighter conditions, along with ongoing risks from New York’s aging fossil fleet.
- NYISO’s independent market monitor, Potomac Economics, says state policy uncertainty has narrowed reliability margins and prompted more conservative planning assumptions. It warns that unresolved fossil plants sitting and permitting policies could impede the most economic solutions. Potomac estimates that addressing the identified reliability needs with new fossil generation would cost about $400 million annually by 2036, compared with about $900 million for batteries alone. The Hochul Administration has signaled openness to new gas generation for reliability under the governor’s “all of the above” energy strategy, potentially supporting new fossil generation over the long term.
- The RNA next goes to the NYISO Board for approval. NYISO will rerun the analysis to incorporate any changes to key inputs and, if reliability needs persist, issue a solicitation for solutions, expected in spring 2027.
ERCOT Energy Summary
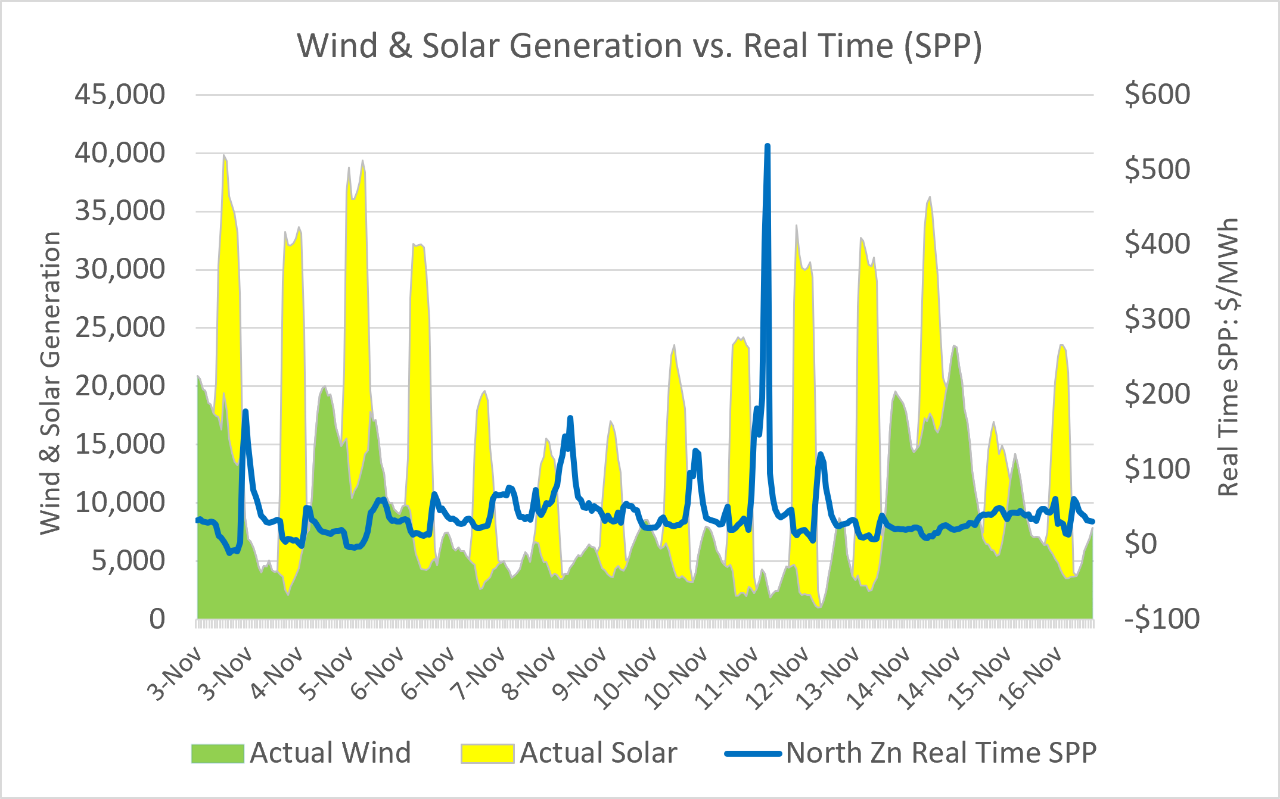
- Houston saw day time highs reach 81F on the 12th & 13th last week but the other major cities were in the 70’s before a cold front arrived over the weekend bringing daytime temperatures down into the 50’s. Wind took a break last week at only 3-7 GW on a flat average basis before rebounding with the cold front to 17 GW on 11/14 before falling off again. Solar hit 10 GW on Thursday (12th) & Friday (13th) before clouds rolled in to crush output to 5 GW for the weekend.
- For this week of 11/16, dry conditions will persist across Texas through the balance of this week, with a day-over-day warming trend bringing very mild air through the weekend. Storms in the West will begin moving through next week and cool us down, but a lack of cold air in the pattern means temperatures will likely only fall to normal (low 70’s) or first category below normal (upper 60’s) at best. This pattern continues into the 11-15 day period, with the models becoming more mixed toward days 14 and 15 and some operational models showing below-normal temperatures. I don't see a strong connection to cold air in the pattern, so the best bet is a few degrees below normal.
- Turning to renewables, wind generation will be taking a vacation as it will only be averaging 8-15 GW on a flat average next week. Again, there will be steady rain and cloudy skies next week as solar will average 5-6 GW on flat average basis through the weekend.
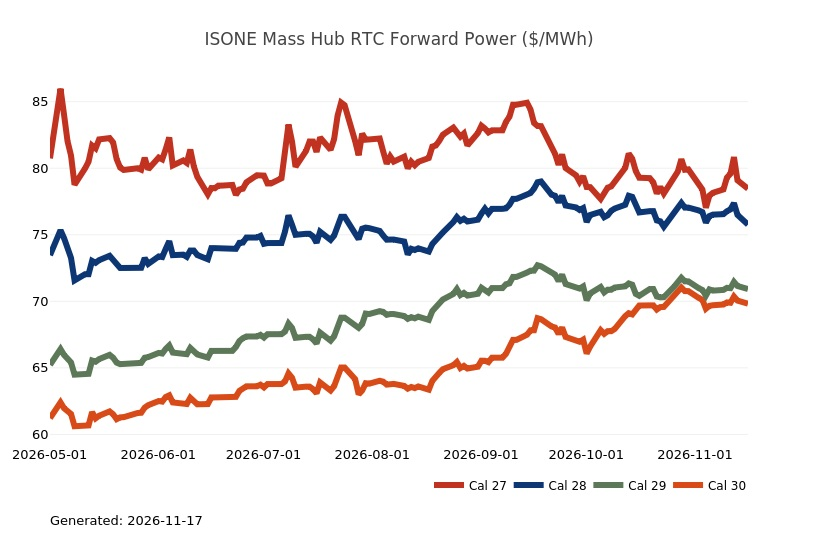
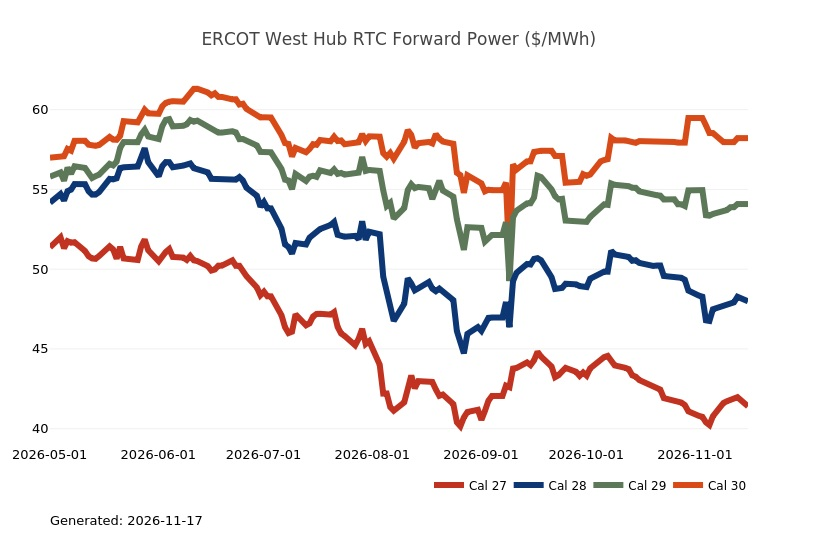
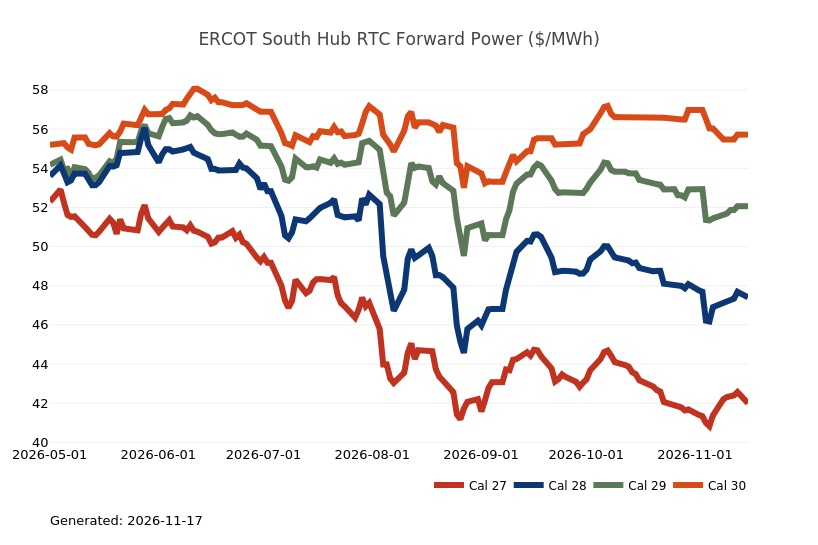
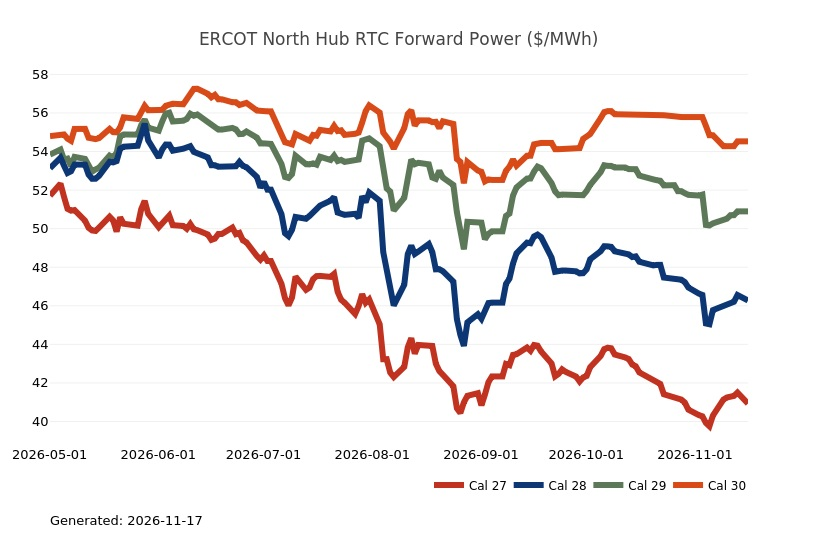
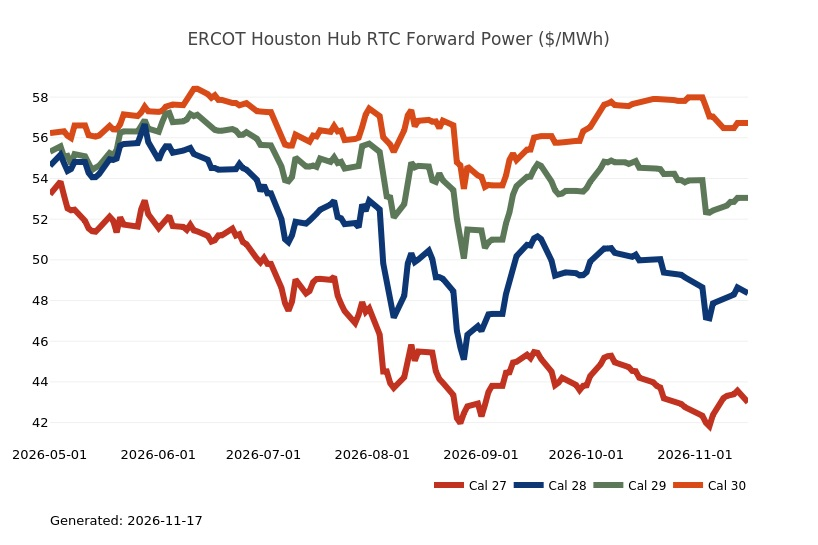
- Over the past week ending 11/13, forward prices in ERCOT prices reversed some or all of the prior week losses. They were up 3% for 2027, 1.8% for 2028 and 1.3% for 2029. Attention remains focused on what is now expected to be a 150-page audit report of data centers due on December 10th.
ERCOT Real Time Prices
Source: ERCOT
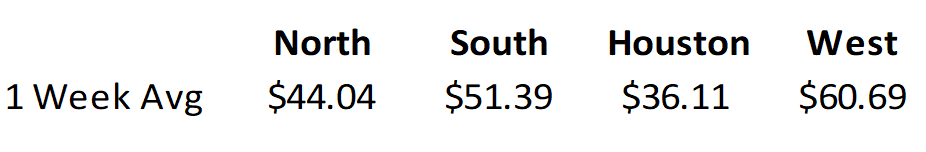
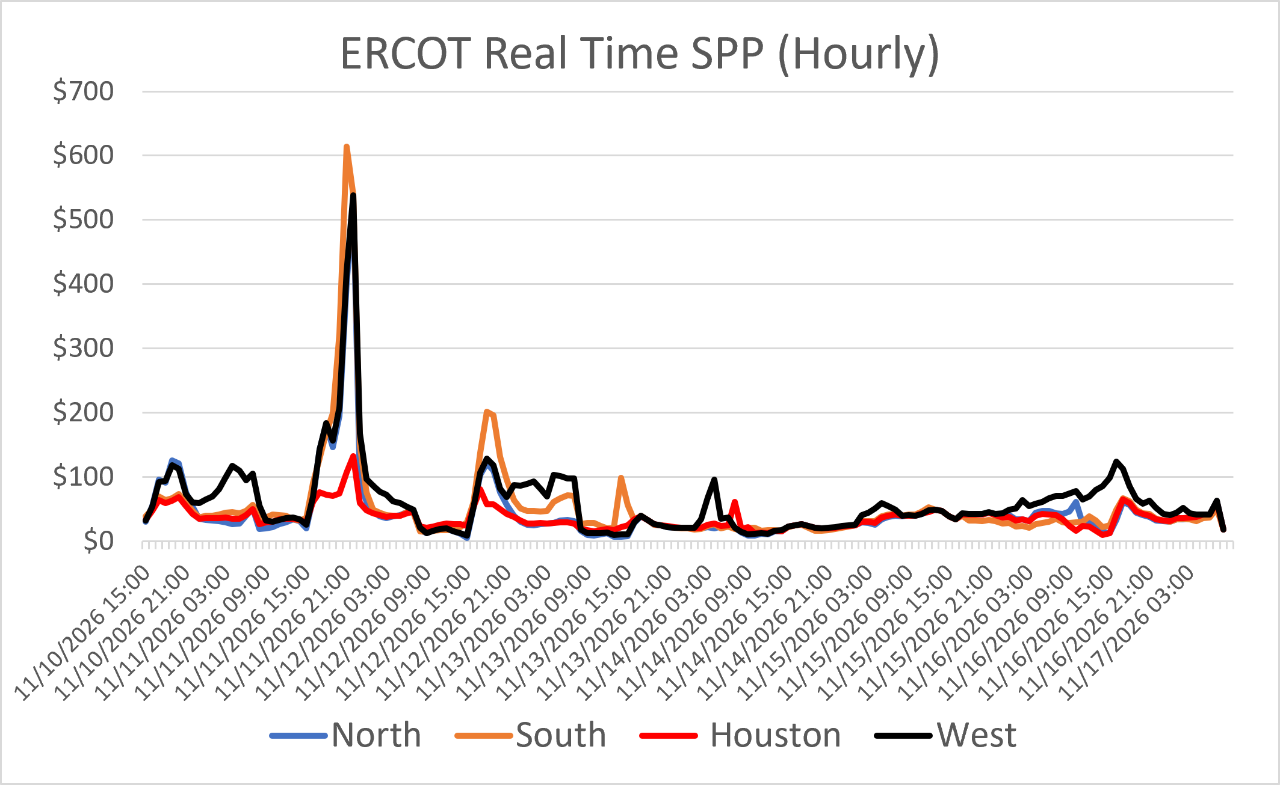
- Real time prices were mostly quite last week with the one exception being HE 22 (9-10pm CT) on Veteran’s day where they averaged $531/MWh for the North zone & $613/MWh for the South zone. They were driven by congestion as Houston and West zones averaged under $120/MWh each. Wind was low that day and a possible driver of congestion.
Recent Solar, Wind and Battery Milestones:
- There have been no new records set in ERCOT over the past month. ERCOT notched another new battery CHARGING record of 12,299 MW on September 10th at 9:15 am CT, displacing the one from September 1st of 11,460 MW. The discharge record from August 23rd of 13,255 MW at 7:45 pm CT still stands.
- The solar output record of 35,281MW from 7/30 still stands. This surpassed another record set on July 27th for 34,700 MW. The top 10 days for ERCOT maximum solar have occurred so far this year in July and August.
- The new all-time maximum load record of 91,089 MW from July 22nd still stands but August has traditionally seen ERCOT set its new peak loads. ERCOT set a new maximum solar output record 35,281 MW on July 30th and the second new one this week. On July 8th ERCOT set a new discharge record for batteries of 11,674 MW breaking the record of 10,372 MW set back on March 13th.
- June 25th saw a new record output for combined renewables of 51,974 MW, the second this week and breaking the previous record of 47,919 MW on May 14th. ERCOT set a new wind record last week at 28,928 MW on May 17th at 11:50 PM CT as winds were strong overnight. The previous maximum wind record of 28,715 MW set on 3/14 at 10:55 pm CT. ERCOT also set a maximum renewables output of 47,919 MW on May 14th at 3:15 pm CT. This was ~900 MW higher than the previous record from last June.
Generator Outages
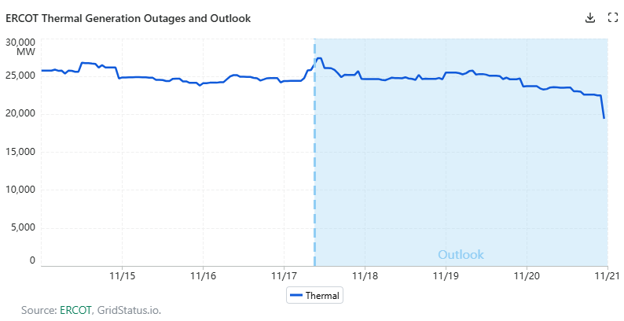
- Thermal generation outage levels are in full swing as we start November. Outages have been holding steady at 25 -30 GW level since October, and this will continue through the balance of November.
https://www.gridstatus.io/graph/ercot-outages?iso=ercot&outageType=thermal
Source: ERCOT & Grid Status
TX Legislature, PUCT, & ERCOT News:
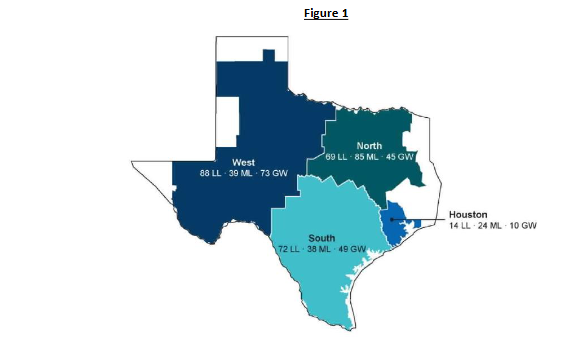
At the November 5th PUCT Open Meeting ERCOT’s General Counsel Chad Seely provided an update on the Batch Verification process and how ERCOT has broken the audit into three work streams so as to account for loads as small as 10 MW to 75 MW so as to account for small and medium loads. ERCOT staffed issued 132 requests for information (RFIs) in late October to transmission and distribution service providers (TDSPs), covering interconnection requests for loads ranging from 10 MW to 75 MW that were received since June 2026. A medium load in ERCO is defined as anything between 25-75 MW. ERCOT’s intent is to capture the “actual requests that came in from the summer up till October” as stated by Mr. Seely. The RFI’s were requesting load type, requested megawatts, location, energization dates and ramp, whether the loads are behind the meter and project names.
Figure 1 shows the breakdown of respondents by region and size at a macro level by both large and medium loads and total GW of capacity. Mr. Seely explained that by lowering the threshold to 10 MW it would cast a wider net to see what the impact of those small to medium loads would be on the ERCOT system. The West zone had the largest queue of load growth at 73 GW followed by 49 GW for the South zone and 45 GW of the North zone. The West zone has the smallest population density so that would reduce impact to neighboring communities. Finally, Mr. Seely noted that ERCOT will have obligations to comply with NERC’s adoption of 50 MW as the Large Load threshold for Large Computational Loads (LCLs). He did not elaborate on any details as to how ERCOT will try to apply that threshold for standard industrial Loads as well.
Source: Customized Energy Solutions
CAISO, Desert Southwest and Pacific Northwest Energy Summary
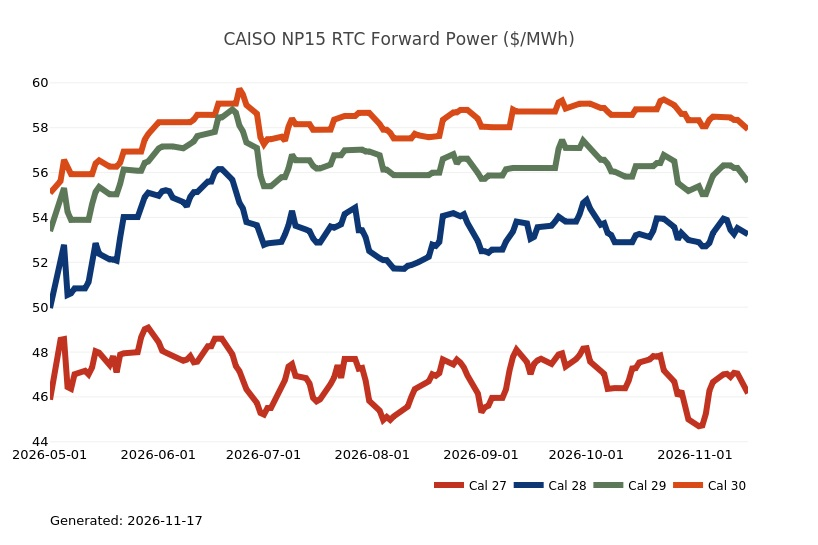
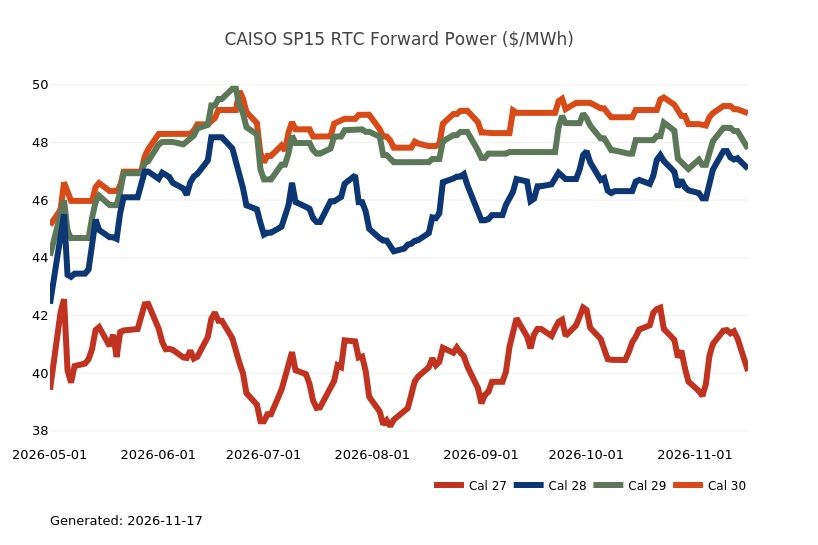
- California and the broader West are shifting away from last week's unseasonable warmth into an active, stormy pattern that will bring seasonable to below-normal temperatures from the Rockies westward. A storm track will deliver heavy precipitation to California alongside notable snowfall in the Sierras and across the interior mountain ranges this week, likely adding a few percentage points of improvement to a slow start to the water year. Looking further ahead, the weather forecast points to continued storminess and near- to above-normal temperatures across the West through late November and early December. This aligns with NOAA's winter outlook and a strengthening El Niño event—currently holding a Niño-3.4 index of +2.1°C with an 83% chance of reaching historic strength through December. Under this scenario, California and the Desert Southwest sit on the wet side with above-normal and normal temperatures expected, respectively, while the Rockies split between a wet south and a dry, warm north. Conversely, the Pacific Northwest likely faces a dry, warm winter with 50% to 60% odds of above-normal temperatures, compounding an already constrained regional water supply forecast sitting at 78.7% of normal.
- The Golden State’s natural gas mkt is moving into the first below normal stretch of weather with storage inventories trailing prior-year levels, even as mild early-November weather allowed utilities to extend late-season injections. At the halfway point of November, PG&E’s storage balance reached 172.1 Bcf, sitting 14.6 Bcf below last year and a little over 6 Bcf behind 2024, while SoCalGas stood at 106.5 Bcf, roughly 2.0 Bcf behind last year’s pace. Spot prices softened slightly over the weekend package, with PG&E city gate settling at $3.37/MMBtu and SoCal’s gate at $3.57/MMBtu. However, that dynamic is shifting rapidly as colder air pushes into the Golden State, driving weekday demand higher to 2.39 Bcf/d on PG&E and 1.86 Bcf/d on SoCalGas. With daytime highs in the LA Basin dropping from the mid-60s into the low 50s by end of week and Sacramento dipping into the mid-40s, rising heating loads will quickly narrow injection capacity and push both systems toward net withdrawals.
- Dispatchers at the CAISO will have to deal with cloud cover and persistent precipitation across SoCal suppressing midday solar output, lending firm price support to daily index settles and increasing reliance on thermal gens. On the nuclear front, California’s baseload generation received a major boost as Diablo Canyon Unit 1 completed its refueling outage ahead of its 38-day schedule, returning to full output on Friday the 13th and restoring the facility to 2.2 GW. In contrast, the Desert Southwest remains down 1.3 GW of baseload capacity as PV Unit 1 entered its 42nd day offline for refueling, keeping the Arizona complex at 2.6 GW. Looking into the winter months, energy buyers across the Western Interconnect must navigate a sharp regional hydro divide: wetter conditions in California and the Desert Southwest should bolster local hydro and trim gas burn, whereas a dry, warm Pacific Northwest threatens to tighten southbound transmission imports from a hydro fleet already starting on its back foot. Speaking of Pacific Northwest hydro, here’s your pre-Thanksgiving energy geek tidbit: At 6,809 megawatts of capacity, the Grand Coulee Dam in Washington isn't just the largest power station in the United States – it is the primary frequency and inertia anchor for the entire Western Interconnect. Its Third Power Plant houses penstocks 40 ft in diameter, each capable of moving twice the average flow of the Colorado River to spin massive turbines that feed over 22 regional transmission lines. Because spinning steel hydro turbines provide heavy physical rotational inertia, Grand Coulee acts as a shock absorber when a major thermal unit or transmission line trips offline thousands of miles away. However, its flexibility is strictly governed by the quality of the water yr and non-power rules like seasonal flood-control curves and spring salmon-migration spill mandates which dictate how much water BPA can hold back for electricity marketing.
Stay up-to-date on the latest energy news and information:
Coming soon from Constellation Customer Insights: Help us provide you with greater service by completing our online study later this month. For a limited time, eligible customers can choose to accept an incentive for taking the time to provide feedback.
- Energy Market Intel Webinar - Register for our next market update webinar on Wednesday, November 18 at 2 p.m. ET when the CMG team will provide insights on market factors currently affecting energy prices, such as weather, gas storage and production, and domestic and global economic conditions.
- Fortunato & Friends Webcast - Stay tuned for information regarding our next Fortunato & Friends webinar featuring Constellation's Chief Economist and a special guest
- Energy Terms to Know - Learn important power, gas and weather terms.
- Sustainability Assessment - We invite you to complete a brief assessment that helps us learn where your company is in building and/or implementing a sustainability plan. Through these insights, Constellation can customize solutions to meet your needs.
- Subscription Center - Sign up to receive updates on the latest market trends.
Questions? Please reach out to our Commodities Management Group at CMG@constellation.com.